Cash Flow Management for Small Businesses: A Practical UK Guide
Cash flow is often the difference between a business that feels stable and one that is constantly firefighting. This practical guide explains how small UK businesses can improve cash flow management through better invoicing, tighter payment terms, simple forecasting, and realistic contingency planning.
By Sophie Bennett · Published 4 October 2026 · Updated 7 October 2026 · 10 min read
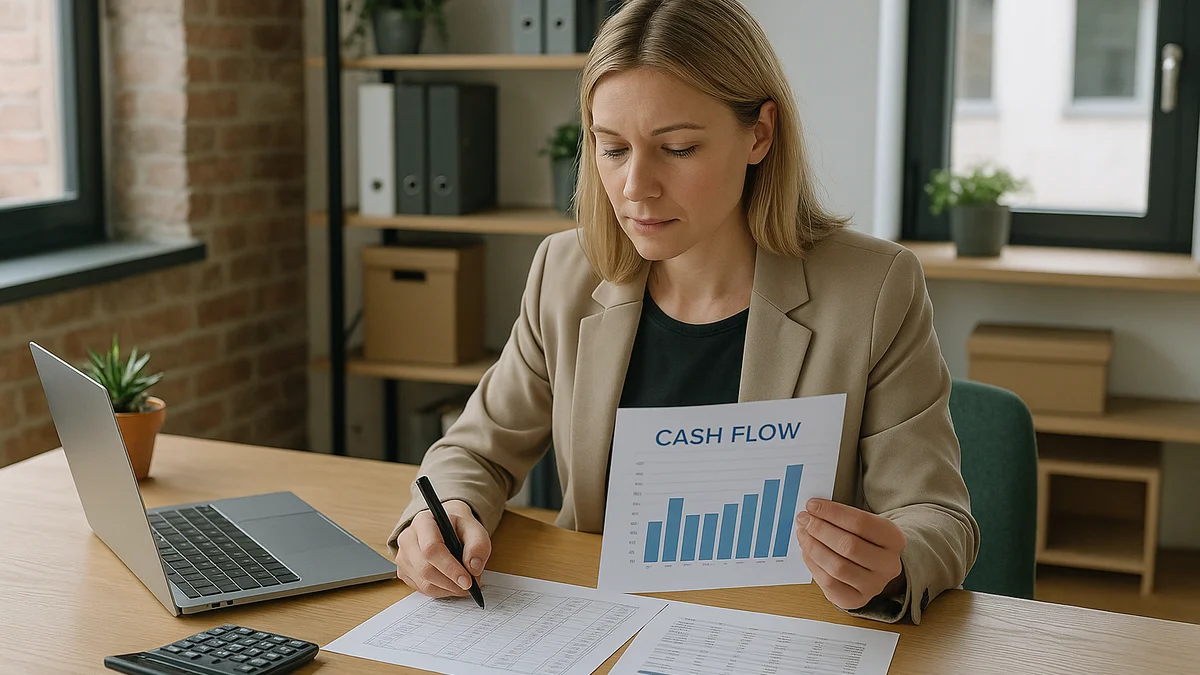
Why cash flow deserves your first hour, not your last
For many small businesses, cash flow is not an accounting detail. It is the day-to-day reality that decides whether suppliers are paid on time, wages go out smoothly, and the business can take on new work without strain. Profits matter, but cash arriving late can still leave a business unable to operate comfortably.
Cash flow management for small businesses is therefore about timing as much as total income. A sale that looks healthy on paper may not help if the invoice is unpaid for 30 days, or longer. By contrast, a modest but reliable inflow of cash can keep a business steady and reduce stress across the team.
This guide focuses on practical actions UK small businesses can take now: improving invoicing, managing payment timing, building a forecast, and knowing where official support may be available.
Key takeaways
- Cash flow is about when money moves, not only how much a business earns.
- Clear invoicing and clear payment terms help reduce avoidable delays.
- A simple rolling forecast is often more useful than a complicated spreadsheet.
- Limited company directors remain legally responsible for company records, accounts and reporting, even if tasks are delegated.
- If your business needs support, official UK business finance and support schemes may help you find local assistance.
What cash flow management actually means
Cash flow management is the process of making sure your business has enough money coming in at the right time to cover what needs to go out. That includes rent, payroll, supplier bills, tax payments, software subscriptions and any borrowing commitments.
In simple terms, you are trying to avoid a timing gap. The gap can appear even when sales are strong, particularly if customers pay late or if your business must buy stock, materials or labour before it is paid itself.
Profit and cash flow are not the same
| Area | What it shows | Why it matters |
|---|---|---|
| Profit | Whether income exceeds costs over a period | Shows whether the business model is viable |
| Cash flow | When money actually enters and leaves the bank account | Shows whether the business can pay bills on time |
A business can be profitable and still run short of cash. That is why cash flow should be monitored separately from management accounts or year-end figures.
Start with the biggest cash-flow pressure points
Before you build a spreadsheet, identify where pressure tends to build in your business. Most small businesses have a few recurring causes of strain:
- customers paying late
- stock bought too early
- large supplier invoices falling due before customer money arrives
- seasonal trading patterns
- tax or insurance bills arriving in clusters
- unplanned repairs or one-off spending
Once you know the pressure points, you can decide where to intervene first.
Practical step: map your cash cycle
- List the moment you incur a cost.
- List the moment you invoice or bill a customer.
- List the average time it takes to receive payment.
- List fixed outgoing dates for rent, payroll and suppliers.
- Note any peaks and troughs across the year.
This does not need to be elaborate. A short monthly view is often enough to reveal the biggest risks.
Invoice properly and invoice promptly
If you sell goods or services to a customer in a business-to-business transaction and both parties are registered for VAT, you need to give the customer an invoice by law. GOV.UK also states that an invoice is not the same as a receipt: a receipt acknowledges payment, while an invoice sets out what must be paid and when.
For cash flow purposes, invoicing quickly is one of the simplest improvements a small business can make. The faster you bill, the sooner payment can arrive. Delays in invoicing are often avoidable and can create an entirely artificial cash squeeze.
What a useful invoice should do
At a practical level, the invoice should make it easy for the customer to pay you without questions or delay. GOV.UK says an invoice must include certain information such as how much the customer needs to pay and when the customer must pay it.
That means you should make the payment date visible and unambiguous. The easier it is for the customer to understand the request, the less likely it is that payment sits in someone’s inbox waiting for clarification.
Example: a design studio tightening its billing routine
A small design studio completes a website project in two stages. Previously, it waited until the end of the project to invoice everything at once. That left the business under pressure because subcontractor costs were paid earlier than customer money arrived.
The studio changes its process so that each project starts with a staged invoice and a second invoice at delivery. The work is the same, but the cash timing is better aligned with the costs. That reduces the need to dip into reserves for routine spending.
Make payment terms work for the business, not against it
Cash flow often improves when payment terms are designed deliberately rather than copied from past practice. If your business routinely waits too long to be paid, your terms may be helping customers more than they are helping you.
When setting terms, think about three things:
- how long you can realistically wait for cash
- what your customer is likely to accept
- how the terms affect your own supplier and payroll commitments
Terms should be commercial and workable. Overly generous terms can create avoidable strain, while overly strict terms may discourage sales. The aim is a balance that reflects the business’s actual cash needs.
Example: comparing two payment approaches
| Approach | Benefit | Risk |
|---|---|---|
| Invoice only on completion | Simple for the customer | Business may fund costs for longer |
| Deposit plus staged invoicing | Brings cash in earlier and reduces exposure | Requires clearer project milestones |
For many small service businesses, staged billing can be more stable than a single end-of-project invoice. For product businesses, deposits or partial payments may help cover stock or production costs.
Forecast cash, not just sales
A cash forecast is one of the most useful tools available to a small business. It does not need to be complicated. The point is to see ahead far enough to avoid surprises.
At minimum, a forecast should show expected cash in and cash out by week or month. Include:
- expected customer receipts
- supplier payments
- payroll
- rent and utilities
- tax and insurance payments
- planned purchases
- a buffer for unexpected costs
Keep it rolling. Update it regularly so it reflects actual payments, not just the original plan. A forecast is useful only if it stays close to reality.
Practical step: use three scenarios
Instead of one forecast, build three simple versions:
- Base case: customers pay roughly on time
- Slow case: some customers pay later than expected
- Stress case: one or two significant payments are delayed
This helps you decide what action to take early. If the stress case shows a shortfall, you can respond before the account becomes uncomfortable.
Control spending with the same discipline as income
Improving cash flow is not only about chasing payments. It also means controlling when money leaves the business. Many small businesses leak cash through habits that are easy to overlook: duplicate software subscriptions, over-ordering stock, or approving spending without checking timing.
A practical spending review can be done in three stages:
- Identify recurring payments.
- Separate essential from non-essential costs.
- Check whether any supplier terms can be renegotiated.
It is usually easier to improve cash flow by trimming or timing expenditure than by finding large new income quickly.
Useful spending questions
- Do we need to buy this now, or can it wait?
- Can the cost be split into stages?
- Would a smaller order reduce pressure without harming delivery?
- Are we paying for tools or services we no longer use?
Build a reserve before you need it
A cash reserve gives a business breathing room. Even a modest buffer can reduce the need to make rushed decisions when a customer pays late or an expense appears unexpectedly.
For small businesses, the reserve does not need to be large from day one. The important thing is to start deliberately setting money aside when cash is available. A reserve works best when it is treated as a business habit rather than a spare pot for random spending.
One practical method is to move a fixed amount from stronger trading periods into a separate account. Another is to set aside a percentage of receipts from each invoice paid. The method matters less than the consistency.
Know when external support may help
If cash pressure is persistent rather than temporary, it may be time to look at finance or support. GOV.UK has a finance and support page that points businesses to free local support and a range of finance and advice schemes across the UK.
That does not mean borrowing is always the right answer. But it does mean small businesses should not assume they have to solve every cash issue alone. Local support, advice and finance options may help bridge a gap or support growth plans.
If your business is looking for additional capital or cashflow support, GOV.UK also lists a number of finance schemes and providers. The right option depends on the business stage, sector and location.
Example: a retailer dealing with a seasonal gap
A small retailer has a strong trading period in late autumn but a weaker start to the year. Instead of waiting until the slow months arrive, the owner reviews cash flow in advance, reduces discretionary spend during the weaker quarter and speaks to local support resources listed on GOV.UK to see what forms of finance or advice may be available.
The result is not that the business becomes immune to seasonal variation. It becomes better prepared for it.
Limited companies need disciplined records as well as good cash planning
If your business operates as a limited company, cash flow management sits alongside legal responsibilities. GOV.UK says directors must follow the company’s rules, keep company records and report certain information, prepare annual accounts, complete the Company Tax Return, file accounts and the Company Tax Return, tell other shareholders if they might personally benefit from a transaction, and pay Corporation Tax.
You can hire other people to manage some of these tasks day to day, such as an accountant, but the director remains legally responsible for the company’s records, accounts and performance. In other words, cash management is not only operational; it supports compliance.
If records are weak, it becomes harder to understand true cash position, forecast accurately or spot emerging trouble early.
A simple 30-day cash flow reset
If your business needs a reset, use this one-month action plan:
- Days 1-3: review overdue invoices and upcoming bills.
- Days 4-7: update payment terms and invoice wording where needed.
- Days 8-12: build a simple 12-week cash forecast.
- Days 13-18: identify unnecessary spend and pause anything non-essential.
- Days 19-24: check whether customers can be moved to staged billing or earlier invoicing.
- Days 25-30: review results and set a weekly cash review meeting.
This approach works because it is focused and measurable. You are not trying to solve every financial issue at once. You are reducing avoidable friction quickly.
How often should a small business review cash flow?
There is no single answer, but weekly review is often sensible for businesses with tight margins, fast-moving stock, or irregular customer payment patterns. Monthly review may be enough for businesses with steadier income and predictable outgoings. The key is that review should happen before the bank balance becomes a problem.
Many businesses benefit from a short, regular cash meeting covering three points: what came in, what went out, and what is due next. That discipline is simple but effective.
Frequently asked questions
What is the fastest way to improve cash flow?
Often the quickest gains come from invoicing promptly, chasing overdue payments, and pausing non-essential spending. In some businesses, staged billing can also bring money in earlier.
Is cash flow management only for struggling businesses?
No. Strong cash management helps healthy businesses stay stable, plan growth, and avoid unnecessary borrowing. It is a routine management task, not just a rescue tool.
Should I use accounting software for cash flow?
It can help, but software is only useful if the data is accurate and regularly reviewed. A simple forecast that is kept up to date is better than a complex report nobody checks.
Can a limited company director delegate cash management?
Day-to-day tasks can be delegated, but GOV.UK states that directors remain legally responsible for the company’s records, accounts and performance.
Where can a small business look for support?
GOV.UK’s business finance and support page is a useful starting point for free local support and finance-related schemes.
Conclusion
Cash flow management for small businesses is practical work, not theory. Invoice quickly, make payment terms clear, forecast realistically, control spending, and review the position regularly. Those habits will not remove every pressure, but they will make the business steadier and easier to run.
If the business is a limited company, remember that good cash discipline also supports the wider obligations of directors. If cash remains tight, official support and finance resources may help you decide the next step.
Sources / References
- GOV.UK — Invoicing and taking payment from customers
- GOV.UK — Business finance and support
- GOV.UK — Running a limited company
Related articles
How to Check if a Business for Sale Is Profitable
A business can look profitable on paper while hiding weak cash flow, one-off income, unpaid owner labour or costs that will rise after completion. Here is a practical way to test the numbers before you make an offer.
10 October 2026 · 15 min read
How to Value a Business With No Profit
When a business has no profit, a standard earnings multiple quickly loses its value. The better approach is to look at what the business owns, how reliable its revenue is, how dependent it is on the owner, and what the figure is for in the first place.
10 October 2026 · 13 min read
Business Valuation: Methods, Risks and Preparation
A practical guide to business valuation for UK owners: what the figure means, how the main methods work, why the answer is often a range, and how to prepare proper records before you sell, raise funding or plan a change in ownership.
9 October 2026 · 12 min read
How to Sell a Business in the UK: A Practical Guide
Selling a business is part valuation exercise, part preparation project and part negotiation. This guide explains the main sale routes, what buyers will examine, how to present the business, and the legal and tax steps to manage before completion.
9 October 2026 · 13 min read